Learning the process of creating a Simple Personal Budget Using a Spreadsheet is the most effective way to gain clarity over your financial life. By organizing your income and outgoings into a digital format, you transform abstract worries about money into actionable data. Whether you are aiming to pay off debt, save for a major purchase, or simply stop wondering where your paycheck went, a spreadsheet provides the ultimate flexibility.
You do not need complex accounting software or expensive financial tools to get started today. This approach relies on basic arithmetic and a clear view of your habits to help you build lasting security and peace of mind.
Setting Up Your Digital Ledger
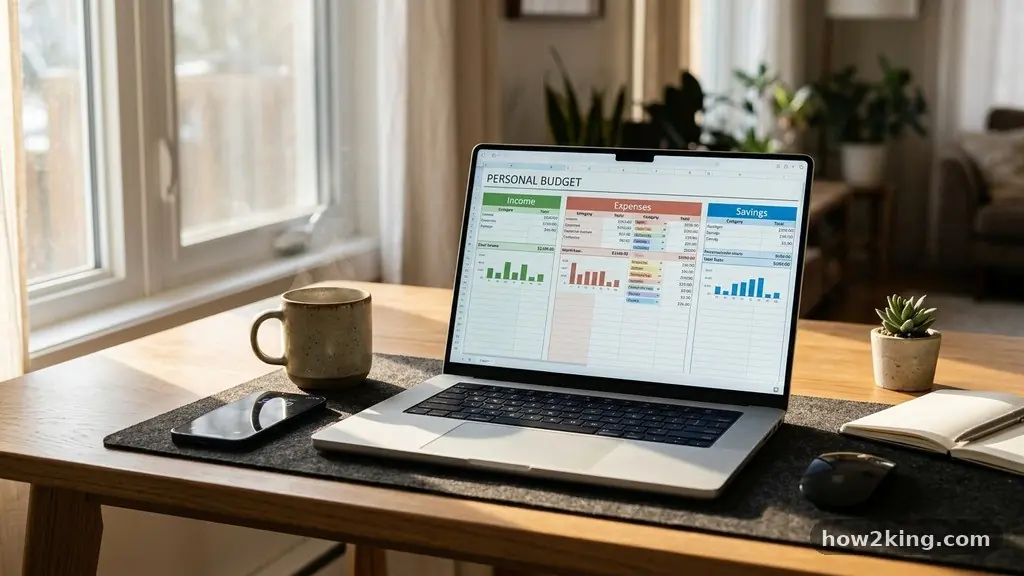
The first step in creating a Simple Personal Budget Using a Spreadsheet involves choosing your preferred software. Both Microsoft Excel and Google Sheets are excellent options, as they offer the basic functions needed for standard household accounting. If you prefer working offline, Excel is a powerful choice with extensive offline capabilities.
Those who enjoy accessing their data from multiple devices, such as a phone or tablet, will find Google Sheets to be highly convenient. Open a blank workbook and prepare to label your columns clearly to ensure your data remains readable over time.
Start by creating three main sections in your first sheet: Income, Fixed Expenses, and Variable Expenses. You might want to dedicate the first few rows to your monthly net income, which is the total amount that hits your bank account after taxes. Beneath that, list your fixed costs, such as rent or mortgage payments, insurance premiums, and recurring subscription fees.
These are the bills that rarely change from month to month, making them the easiest to forecast. Once you have established these categories, you are ready to begin inputting your actual numbers.
Categorizing Your Monthly Income
Before you can determine what you can spend, you must have an accurate picture of what you earn. Most people have a primary salary, but it is important to capture every cent that enters your account throughout the month. If you are a freelancer or have a side hustle, create a specific line item for each source of revenue.
This helps you track the volatility of your income, which is crucial for managing your financial expectations. Use the Consumer Financial Protection Bureau resources to understand how irregular income affects your planning.
Be sure to record your income as a net figure rather than gross. Your paycheck stub will show the difference, but you only have the net amount available for your actual spending. If you share finances with a partner, include both incomes in the same spreadsheet to see the total household cash flow.
This collaborative view is often the first time couples truly understand their collective financial standing. Once your income is listed, use the summation function at the bottom of the list to calculate your total monthly inflow.
Tracking Fixed and Variable Expenses
Expenses usually fall into two distinct buckets: the predictable and the flexible. Fixed expenses are your non-negotiables, such as rent, utility base charges, and internet bills. These should be entered into your spreadsheet with their due dates so you can align your payments with your pay cycles.
Variable expenses, such as groceries, entertainment, dining out, and shopping, are where you have the most room to adjust. These categories often require a bit more effort to track, but they are exactly where you can find extra money to save.
To make the process easier, look at your bank statements from the previous three months to get an average for your variable spending. A simple spreadsheet allows you to create a “Budgeted” column and an “Actual” column side-by-side. This comparison is the heartbeat of effective budgeting because it reveals where you might be overestimating or underestimating your lifestyle costs.
Do not be discouraged if your actual spending exceeds your budget in the first month. Use the difference as a data point to refine your estimates for the following month.
Utilizing Formulas for Automatic Calculation
The true power of using a digital spreadsheet lies in its ability to do the math for you. Instead of pulling out a calculator every time you add a receipt, you should use basic formulas to keep your totals updated in real-time. For example, you can use the SUM function to add up all your expenses automatically.
If you want to see how much money you have left over, create a cell that subtracts your total expenses from your total income. This “Remaining Balance” cell is the most important part of your entire sheet.
You can also use conditional formatting to highlight specific cells based on their values. For instance, you could set a rule that turns a cell red if your spending in a particular category exceeds your budgeted amount. This visual cue helps you spot potential problems before they lead to a budget deficit.
As you become more comfortable with these functions, you can even create charts that visualize your spending habits. Seeing a pie chart of your expenses often provides a much clearer picture than looking at a list of numbers.
Building a Monthly Comparison Table
Organizing your data into a clear table helps you identify long-term trends in your financial health. By creating a structure that spans several months, you can see how your savings grow or where your spending spikes during certain times of the year. The following table illustrates a simple way to structure your monthly summary for better visibility:
| Category | January | February | March |
|---|---|---|---|
| Total Income | $4,000 | $4,000 | $4,200 |
| Fixed Expenses | $2,200 | $2,200 | $2,200 |
| Variable Spending | $1,500 | $1,300 | $1,400 |
| Net Savings | $300 | $500 | $600 |
This layout allows you to compare your performance month-over-month without creating a new file. You can see at a glance if your variable spending is trending down as you become more disciplined. This is also a perfect place to track your progress toward specific financial goals, such as paying off a credit card or building an emergency fund.
Consistency is the secret to making this table work for your long-term success. Update it at the same time each month, perhaps when you sit down to pay your recurring bills.
Common Mistakes to Avoid During Setup
Even with the best intentions, people often run into hurdles when they start tracking their money. One of the most common mistakes is trying to be too granular with categories. If you have a separate category for “coffee,” “snacks,” and “lunch,” your spreadsheet will quickly become overwhelming to manage.
Stick to broader categories like “Groceries” or “Dining Out” to keep the data entry process quick and sustainable. You want this to be a habit you keep, not a chore you dread.
Another pitfall is forgetting to account for irregular annual expenses. Car insurance, property taxes, or holiday gifts can destroy a monthly budget if they are not planned for in advance. Calculate the total annual cost of these items and divide them by twelve to set aside a small amount each month.
By treating these irregular costs like monthly bills, you avoid the shock of a large bill arriving when you least expect it. Finally, do not forget to include a “Miscellaneous” category for those small, unforeseen costs that inevitably pop up.
Frequently Asked Questions About Budgeting
Can I use a pre-made template instead of building my own?
Yes, both Excel and Google Sheets offer built-in templates specifically designed for personal budgeting. These can save you time, especially if you are not familiar with spreadsheet formulas. However, building your own allows you to customize the categories to fit your specific lifestyle perfectly.
How often should I update my budget spreadsheet?
It is best to update your tracker at least once a week to keep your data fresh and accurate. If you wait until the end of the month, you may forget the specifics of your smaller cash purchases. Setting a recurring calendar reminder can help you stay on track.
What if my expenses are higher than my income?
This is a common wake-up call, and it is the exact reason you are tracking your money. When this happens, look at your variable expenses first to see where you can make immediate cuts. If that is not enough, you may need to look at downsizing your fixed costs or finding ways to increase your monthly income.
Do I need to track every single cent I spend?
You don’t need to be perfect to be successful. If you are off by a few dollars, it won’t ruin your financial health. The goal is to track enough information to identify your patterns and make informed decisions about your future spending.
Is it safe to keep my financial data in a cloud-based spreadsheet?
Using tools like Google Sheets is generally secure, provided you follow standard safety practices. Use a strong, unique password and enable two-factor authentication on your account. Avoid accessing your spreadsheet on public Wi-Fi networks whenever possible.
Maintaining Your Financial Momentum
Once you have mastered the basics of creating a Simple Personal Budget Using a Spreadsheet, the challenge shifts to maintenance. A budget is not a static document; it is a living tool that should evolve as your life changes. When you get a raise, move to a new apartment, or pay off a debt, your spreadsheet should reflect those shifts immediately.
This ongoing process of adjustment is what keeps you in control of your financial future. You are no longer just guessing; you are making informed, deliberate choices about how to allocate your resources.
Celebrate the small wins along the way to keep yourself motivated. When you see your savings account grow or your debt shrink, acknowledge that it is a direct result of your commitment to tracking your numbers. Share these milestones with a partner or friend if it helps you stay accountable.
The simplicity of your spreadsheet is its greatest strength, as it removes the barriers to staying organized. Keep your focus on the long-term goal of financial freedom, and let your spreadsheet guide every step of the journey.